Adjustable-rate mortgage (ARM)
A loan whose interest rate can change after an initial period. Read the adjustment schedule, index, margin, caps and worst-case payment—not only the introductory rate.
Definitions for reading a listing, offer, loan estimate or closing package with more confidence.

Legal effect and process differ by state and contract. Use this glossary to prepare questions, then confirm material details locally.
A loan whose interest rate can change after an initial period. Read the adjustment schedule, index, margin, caps and worst-case payment—not only the introductory rate.
The scheduled repayment of principal over time. Early payments on many mortgages contain more interest than principal.
An opinion of value prepared for a lender or another intended user. It is not a structural inspection or a guarantee of resale price.
Annual percentage rate: a broader cost measure than the note rate, designed to include certain finance charges. Compare the same loan type and assumptions.
The federal form that presents final loan terms and closing costs for many consumer mortgages. Compare it with the earlier Loan Estimate.
A recent, genuinely similar closed sale used to support a pricing opinion. Location, condition, date and features matter.
A contract condition that can allow a buyer or seller to proceed, renegotiate or exit if a defined event occurs within a deadline.
Monthly debt payments divided by qualifying gross monthly income. Lenders may calculate it differently depending on the product.
The legal instrument used to transfer an ownership interest. Its effect and recording rules are determined locally.
Money placed under the contract to demonstrate good faith. Who holds it, when it is refundable and dispute rules depend on the agreement and local law.
A neutral holding arrangement for funds or documents; it may also describe a lender-managed account for taxes and insurance.
One common credit-score model. A score is not the whole underwriting file, and the score version used may differ by loan program.
A federal withholding regime that can apply when a foreign person sells U.S. real property. Obtain qualified tax advice early.
An association that may impose dues, rules, assessments and use restrictions. Read its governing documents and finances before committing.
A standardized estimate of loan terms and costs for many mortgages. Use it to compare written offers made on the same assumptions.
Insurance that may protect a lender or loan program if the borrower defaults. It is distinct from homeowners insurance.
A lender’s preliminary assessment based on submitted information and documentation. It is not an unconditional final approval.
The original amount borrowed or the unpaid balance, excluding future interest. Each amortizing payment generally reduces it.
A recurring local tax assessed against real property. Assessment methods, exemptions, bills and appeals vary by jurisdiction.
The collection of legal rights and interests in a property. A title search and title insurance address different risks; neither replaces due diligence.
The lender’s verification and risk-review process before final loan approval. New debts, job changes or large unexplained deposits can matter.
Local land-use rules that affect what may be built or operated on a site. Confirm the exact parcel, use and permit history with the authority.
The value assigned by a local assessing authority for property-tax purposes. It may differ from market value, purchase price and appraised value.
A large payment due at the end of a loan that does not fully amortize during its term. Confirm the amount, due date and refinancing risk.
The verified funds a buyer must bring to closing after credits, deposits and financing are applied. It is broader than the down payment alone.
The sequence of recorded ownership and transfers affecting a property. Gaps, competing interests or recording errors may require further review.
A mortgage structured to meet applicable Fannie Mae or Freddie Mac purchase criteria, including annual loan limits. It is not a guarantee of approval.
A legal right allowing someone to use part of another property for a stated purpose, such as access or utilities. Review location, scope and maintenance duties.
A claim, restriction or right that affects title or use, including liens, easements and restrictive covenants. Its practical effect depends on the document and local law.
An area mapped or regulated for potential flooding. A map zone is one input; investigate elevation, prior events, drainage and insurance for the exact property.
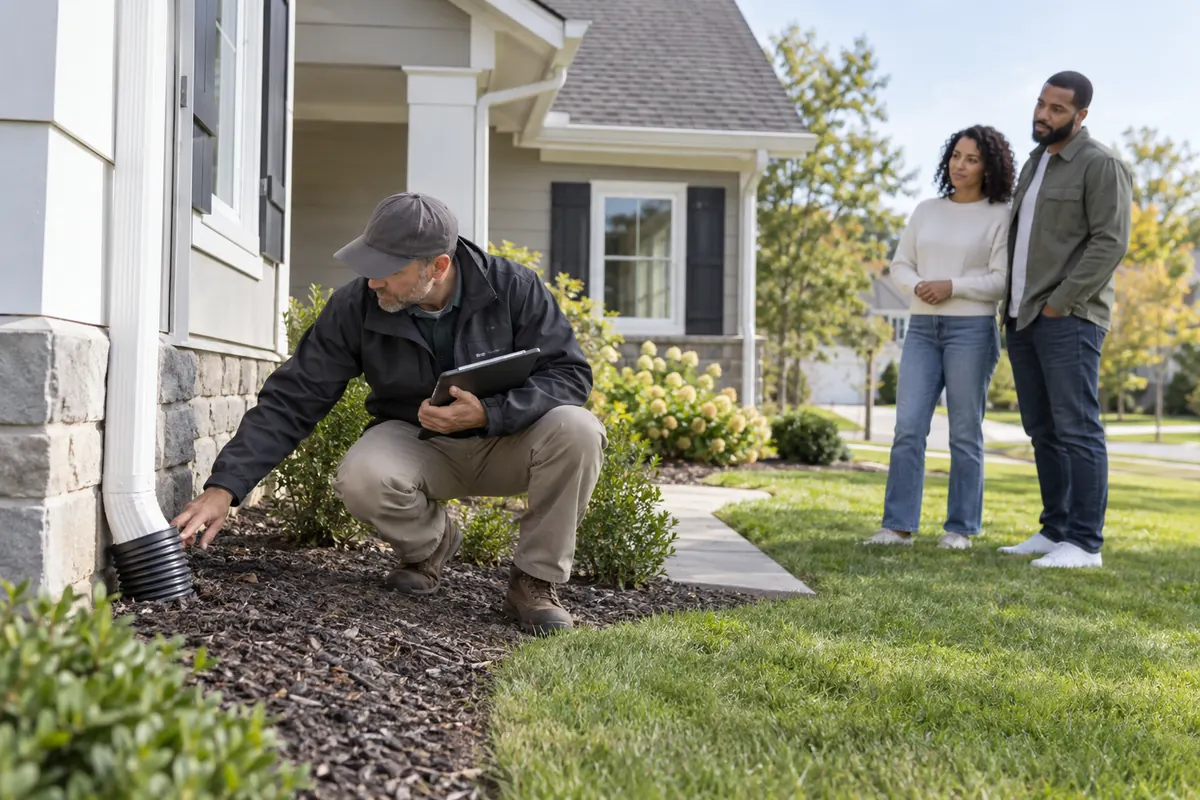
A visual, noninvasive review of accessible systems and components at a point in time. Scope and licensing vary, and specialist evaluations may still be needed.
A legal claim against property that may secure payment of a debt or obligation. Confirm status, priority and release requirements through title and public records.
The loan amount divided by the property value used by the lender. The selected value and combined liens affect the result and related requirements.
A charge associated with processing or originating a mortgage. Compare it together with rate, APR, points and all other lender costs.
Upfront charges expressed as a percentage of the loan amount; discount points may reduce the interest rate. Calculate the break-even period rather than assuming value.
Coverage that may be required on certain conventional mortgages and generally protects the lender, not the borrower. Cancellation rules depend on the loan and law.
An analysis of an association’s major components, remaining useful lives and projected funding needs. Compare it with budgets, balances, projects and assessments.
A charge imposed by an association or authority beyond regular dues or taxes, often for a specific project or shortfall. Confirm approved and discussed assessments.
A professional depiction of boundaries, improvements and selected site features. The needed survey type and reliance rights depend on the transaction and jurisdiction.
A pre-closing check that the property condition and agreed repairs are consistent with the contract. It is not a substitute for an inspection.
A lender agreement that generally holds a mortgage interest rate for a stated period under defined conditions. Record its expiration and extension terms.
A FEMA map used to show mapped flood hazard areas and support certain insurance and lending decisions. Check its panel, effective date and revisions for the exact address.
The geographic area a school district currently uses to assign some students to a school. Assignment and enrollment rules can differ and boundaries may change.
A review of a home’s energy-related systems and building envelope, sometimes using tests such as a blower door or infrared scan. Scope and methods should be documented.
A measured test that uses a temporary fan to estimate building air leakage under controlled pressure. Results need interpretation alongside ventilation and moisture conditions.
The date coverage starts under the issued policy. Confirm it separately from quote, payment and closing dates, including any applicable waiting period.
Available records of reported insurance losses. They are not a complete building-condition history or proof that repairs were completed. For each reported event, distinguish the loss record, repair scope and completion evidence. A missing event in the available extract is an information gap, not proof that no damage occurred.
Money planned for major replacements such as roofs or equipment. Track separately from routine operating costs and disclose how it is treated in a return calculation.
A building authority’s record of a final inspection within a defined permit scope. Confirm the parcel, work, outcome and any outstanding conditions.
Coverage confirmed by the insurer or its authorized representative under stated terms. An indicative quote alone does not establish that coverage is in force.
An escrow analysis finding that funds are below the required target balance. Separate its repayment from the regular deposit for future tax and insurance bills.
Assistance debt whose balance may be forgiven under stated conditions and timing. Read occupancy, sale, refinance and repayment triggers before treating it as a grant.
A loan with payments postponed until a specified event or date. Deferral does not by itself cancel the debt or any accrued interest.
A disability-related change to a housing rule, policy, practice or service under applicable law. Distinguish it from a physical modification and check the relevant official guidance.
A disability-related physical alteration to housing or common areas under applicable law. Permission, cost and restoration responsibilities depend on the circumstances.
A simple cash-flow screen dividing net refinancing costs by positive monthly savings. It does not account for every change in outstanding debt, term or risk.
A geographic unit treated as a county for Census statistics, such as a Louisiana parish, independent city or Connecticut planning region. It may differ from the authority that keeps property records.
A notice explaining that information in a consumer report contributed to a denial or less favorable rental terms, with details of the reporting company and dispute rights.
The amount by which an agreed purchase price exceeds the lender’s appraised value. The contract determines whether either party can renegotiate or exit.
Evidence that an insurance arrangement is in place or being issued, subject to its stated terms. Confirm effective date, limits and lender acceptance.
A major replacement or improvement with benefit beyond routine maintenance, such as a roof or HVAC system. Investors should reserve for these costs separately.
The amount the policyholder typically bears before insurance pays on a covered claim. Some policies set different deductibles for wind or other hazards.
An upfront mortgage charge commonly calculated as a share of principal in exchange for a lower quoted rate; compare its cost with expected time in the loan.
A contract-defined window for inspections, document review and other investigations. Rights and notice requirements depend on the actual agreement.
Separate coverage for specified flood losses, often outside a standard homeowners policy. Check eligibility, waiting period, limits and exclusions for the address.
The federally required information package for most covered pre-1978 residential sales or leases, including known hazards and available records. It is not proof of absence.
Work intended to reduce a hazard, such as a radon-reduction system or drainage improvement. Verify scope, qualified installer and post-work result.
An arrangement to buy electricity generated by a system generally owned by a third party. Review price changes, transfer approval and obligations at sale.
A cost collected at closing for a future ownership period, such as insurance or prepaid interest. It differs from a lender origination charge. When comparing estimates, retain the period and payment date beside each item. A larger advance for a longer coverage period is not necessarily a higher price for equivalent coverage; ask the issuer to explain the basis.
A naturally occurring radioactive gas that can accumulate indoors. Only a properly conducted test establishes the level in a particular home.
A consumer report used in rental decisions that may combine credit, rental and other background data. Applicants can seek a copy and dispute inaccuracies under applicable law.
A scheme that redirects a legitimate payment to a fraudulent account, often through impersonated closing instructions. Independently verify the recipient and account before sending.
A policy settlement basis that accounts for depreciation. Confirm the applicable method and deductible rather than equating it with replacement cost.
Use it in a decision →
Coverage using a replacement-cost basis under the policy’s conditions. The dwelling limit, repair requirements and exclusions still matter.
Use it in a decision →
Policy coverage that may pay qualifying extra living costs after a covered loss. Verify the event, accepted expenses, amount and time conditions.
Use it in a decision →
Insurance for a tenant’s own coverage needs, potentially including belongings and liability. It is separate from the landlord’s building insurance.
Use it in a decision →
Property coverage arranged for a disclosed rental use. Ask about building damage, liability and rental-income conditions in the issued policy.
Use it in a decision →
A document modifying an insurance policy. Keep its scope and effective date with the policy; a request or quote is not the issued change.
Use it in a decision →
Housing decision support through a HUD-participating agency. Verify the agency and service; counseling is not loan approval or legal representation.
Use it in a decision →
A rural housing financing route involving approved lenders and USDA program requirements. Area eligibility alone does not approve a borrower.
Use it in a decision →
A VA document supporting home-loan benefit eligibility. Keep it distinct from the lender’s underwriting and final approval.
Use it in a decision →
A mortgage insured through FHA for approved lenders. Mortgage-insurance costs and actual loan terms belong in the borrower’s comparison.
Use it in a decision →
A refinance that provides additional borrowed cash after prior debt and relevant costs. Reconcile cash received separately from the new total loan balance.
Use it in a decision →
A funding arrangement that subsidizes early mortgage payments. Read the agreement and permanent note terms, including the payment after support ends.
Use it in a decision →
A lender process for reviewing concerns about an appraisal, supported by relevant evidence. It does not guarantee a higher value.
Use it in a decision →
A restriction on access to a credit report for new-credit checks. Coordinate any temporary lift directly with the relevant bureau; it does not correct errors.
Use it in a decision →
A credit-report alert calling for identity verification before new credit. FTC distinguishes it from a freeze that restricts report access.
Use it in a decision →
A new-home warranty with defined provider, components, periods and notice requirements. It differs from a paid home service contract.
Use it in a decision →
An occupancy agreement associated with cooperative shares. Review the actual agreement and jurisdiction; do not assume condominium ownership.
Use it in a decision →
A housing model where the trust may retain land and sell the home under a ground lease with affordability restrictions. Read the specific program.
Use it in a decision →
A lease for use of land with its own rent, term and obligations. Have ownership, transfer and financing implications explained locally.
Use it in a decision →
The pipe connecting a dwelling to the water main. Ask the utility about materials and ownership; unknown material does not establish the absence of lead.
Use it in a decision →
A state-created agency involved in financing affordable housing. Its website is a starting point for program research; eligibility, available funding and application routes must be checked for each program.
Use it in a decision →
For a stated loan-holding period, the interest paid plus the included net loan charges. Principal repaid reduces debt and is tracked separately. Comparisons must state exclusions such as mortgage insurance, penalties and the time value of money.
Use it in a decision →
An American Community Survey estimate describing a stated collection period. A five-year estimate combines observations across five years rather than describing one day at the end of the period.
A measure of sampling uncertainty published with ACS estimates. The estimate, margin of error, period and measured population belong together; a numerical ranking alone does not establish a statistically significant difference.
The point at which a borrower becomes contractually obligated on a loan under applicable state law. It can differ from funding, recording and handover; the lender must confirm the relevant disclosure timetable.
Use it in a decision →
The unit and period attached to a rental quote, such as dollars per square foot per year or a monthly amount for the whole unit. Normalize period, area convention and excluded charges before comparing two quotes.
Rent that would be received with full scheduled collection before vacancy and credit losses. State the rent schedule and period; it is not evidence that every payment will arrive.
Potential income adjusted for the stated vacancy and credit-loss assumptions, plus included other income. Explain which income lines are adjusted.
Scheduled principal and interest payments for a stated period. Keep it separate from operating expenses, capital reserves and income taxes.
A stated income measure divided by debt service for the same period. NOI divided by annual principal and interest is one illustration; a lender may use different income adjustments.
The share of potential rent needed to fund the specified expenses, reserves and debt after included other income. This is a scenario under stated cost assumptions, not a predicted occupancy rate.
A claim amount initially withheld for depreciation that may become payable if the policy conditions and required proof are met. It is not automatically an additional payment on top of the full replacement estimate.
The amount to which a policy deductible percentage applies. It may be a coverage limit rather than the repair bill; confirm the actual contract before calculating.
The locally applicable completion and inspection process for a permitted project. An issued permit and completed final inspection are separate records.
The date to which a valuation refers, distinct from the report delivery date or later sale date. Preserve it when comparing assessments, appraisals and transactions.
Ownership costs incurred while a transaction is pending or a property is held. Define included items and distinguish expense from loan principal reduction.
A tax measure derived from the applicable starting basis and permitted adjustments. It is distinct from remaining mortgage debt, market value and cash equity; retain purchase and improvement records.
The value to which the relevant taxing rules apply after applicable adjustments or exemptions. Names and calculation rules vary by jurisdiction; it is not automatically the asking price.