


FINANCING
Compare Loan Estimates line by line
Normalize the loan assumptions, isolate lender-controlled charges and reconcile payment, cash to close and rate-lock risk.
Read the file
The national guide to understanding and comparing American real estate with patience and a clear method. From your first search to the keys to your next home, we help you place the price inside a complete budget, understand the documents, recognize local risks and prepare better questions for every professional.
America’s property market is vast, deeply local and full of differences that do not appear in a listing. We explain every stage, immediate and future costs, documents that deserve careful reading and essential checks in plain language you can turn into an action list.
From New England to the Pacific, every state has its own rules, taxes, risks, lifestyles and opportunities. Choose a state, then narrow your search to the county and city that fit your plans.
Explore all 50 states GA
Atlanta combines a major employment center with a wide, multi-county housing market. Commute patterns, school districts, municipal boundaries and property-tax treatment can change within a short distance.
Open guide TX
Austin is a fast-changing technology and government center whose housing choices extend well beyond the city line. Taxing districts, utility providers, commute exposure and development rules deserve parcel-level review.
Open guide MA
Greater Boston is a municipality-by-municipality market shaped by transit, older housing stock, universities and a constrained development pattern. The legal and physical condition of each building can matter as much as location.
Open guide NC
Charlotte anchors a cross-county and cross-state employment region. Buyers should compare North Carolina and South Carolina locations with the same assumptions for taxes, insurance, commuting and public services.
Open guideMajor cities, family neighborhoods, coastlines, mountains and fast-growing communities—compare the place, not only the property.
A property never exists in isolation. The asking price is only one part of the decision: financing, taxes, insurance, physical condition, local rules, access to work and services, daily life and resale potential all matter. Our guide connects those pieces so an attractive home can also become a sustainable choice.
A sound real estate decision starts with five answers: what the property is for, what it truly costs, which local evidence matters, what must be verified at the address and which condition would make you walk away.
A primary home, rental, resale or seasonal property requires different financing, tax, management and exit criteria.
Choose a guideAdd closing cash, payment, tax, insurance, dues, utilities, maintenance, transport and reserves—not only the price.
Open calculatorsCompare the same area, property type, condition and period. A state average never replaces recent micro-market comparables.
Explore statesVerify parcel, title, flood, fire, insurance, permits, association rules, zoning and rental use with current sources.
Check sourcesWrite down cost, repair, timing and risk limits, plus the future resale or management plan, before falling for the property.
Use checklistsIf a material claim has no source, date or accountable party who can confirm it, treat it as an open question—not a fact.
A good search does not end when you find a beautiful kitchen or a pleasant neighborhood. It continues with conservative numbers, current documents and an honest view of the life you will have after closing.
Calculate a comfortable payment, then add taxes, insurance, utilities, association dues, maintenance, commuting and an emergency reserve. The goal is not to buy at the limit, but to keep room to live.
Read reports and inspections as the building’s history. Separate ordinary maintenance, upcoming repairs and issues that could affect safety, insurance, financing or resale.
Visit at different times and study mobility, noise, services, nearby projects, natural hazards and use restrictions. Two streets in the same ZIP code can offer very different experiences.
Even a home intended for many years deserves thought about resale or rental. Consider who may want it later, what limits its use and which improvements are likely to preserve value.
From a loan offer to payment safety, building hazards and rental legitimacy, each file identifies the document to request and what to do with the answer.
Normalize the loan assumptions, isolate lender-controlled charges and reconcile payment, cash to close and rate-lock risk.
Read the file
A practical verification protocol for settlement contacts, bank details, last-minute changes and a suspected misdirected wire.
Read the file
Understand what a radon result means, when to retest and how to handle mitigation during a purchase.
Read the file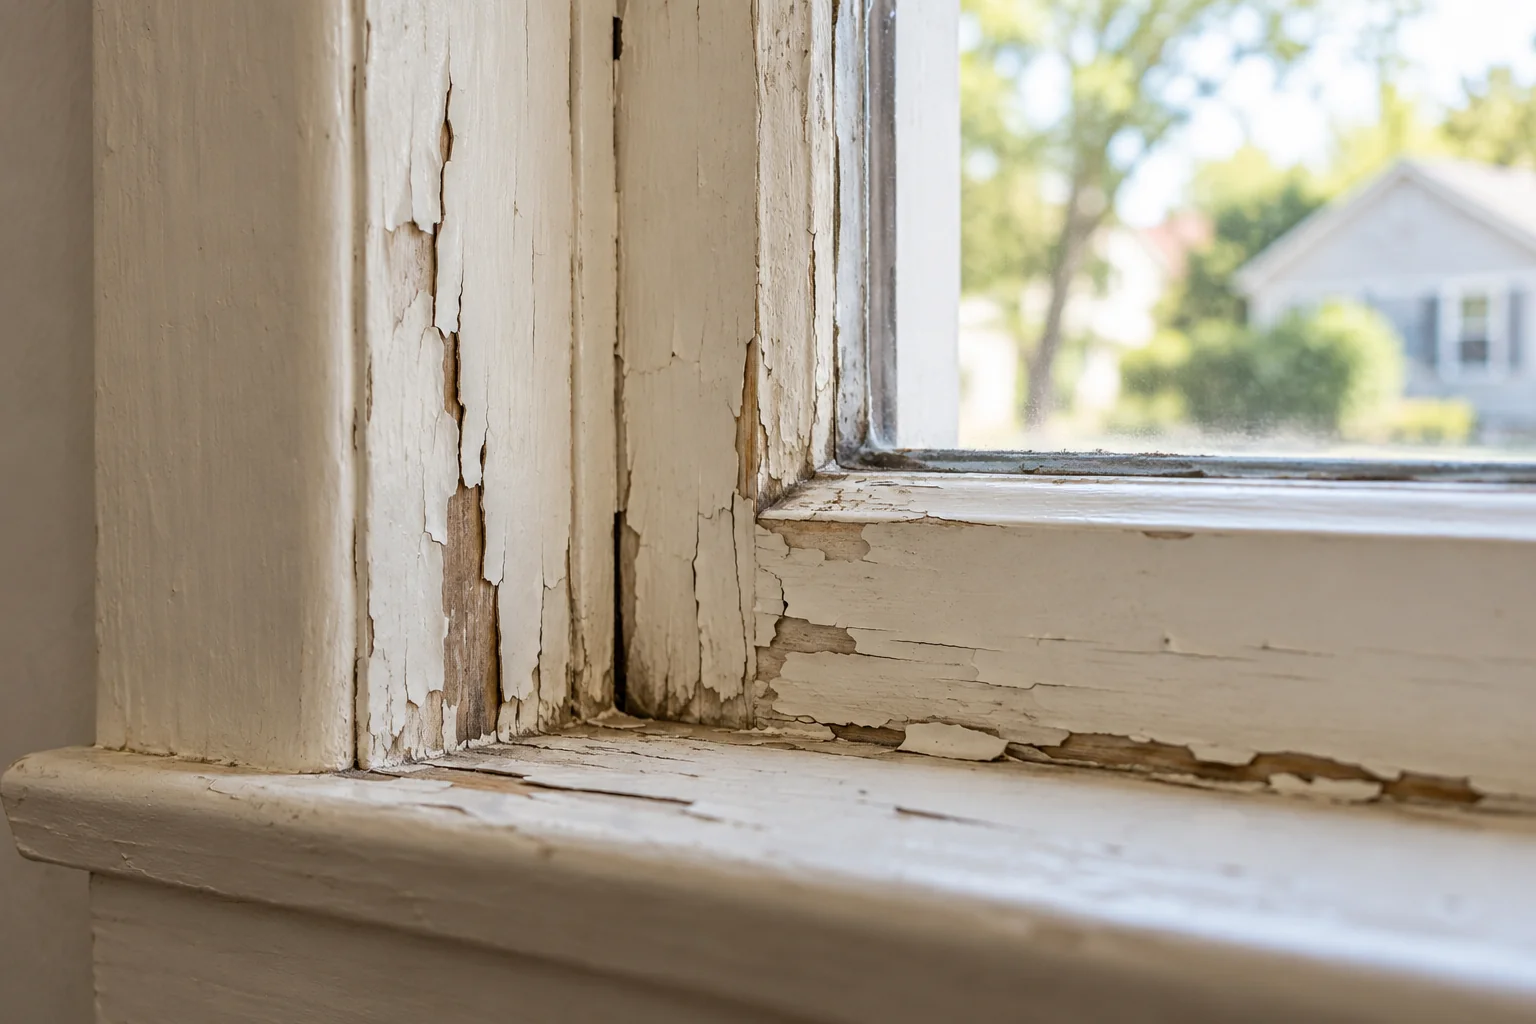
Know which federal disclosure documents to request and how to investigate painted surfaces before renovating.
Read the file
Check the property and manager before paying, protect personal documents and respond to an inaccurate screening report.
Read the fileConcise orientation for common questions; open each answer for the criteria that need property-specific verification.
Browse official sourcesCompare the complete monthly and annual cost: mortgage principal and interest, property tax, insurance, association dues, utilities, maintenance, commuting and a reserve for major repairs. Also check closing cash, physical condition, title, hazards and use restrictions.
Property taxes, insurance availability, disclosure rules, closing practice, permits, zoning, landlord rules and natural hazards can change by state, county, city and even address. State averages are useful context, but a decision needs current property-level and local evidence.
Start with a realistic total budget and your intended use, then compare state and local markets. Review financing before making an offer, build a licensed professional team and preserve enough time for inspection, title, insurance and document review.
Many international buyers can purchase U.S. property, but nationality-based restrictions, state laws, financing, banking, tax reporting and ownership structure require case-specific review. Buying property does not by itself create U.S. immigration or residency rights.
No. It is independent general education designed to help readers organize research and ask better questions. Verify material facts with current official sources and qualified local legal, tax, lending, insurance and real estate professionals.
