Independent knowledge for every U.S. market
Updated for 2026
PA · Northeast

Philadelphia
Real Estate Market Guide

Philadelphia offers rowhouses, condos and detached suburban homes across jurisdictions with different taxes, transfer practices and school systems. Older construction calls for careful systems and permit review.

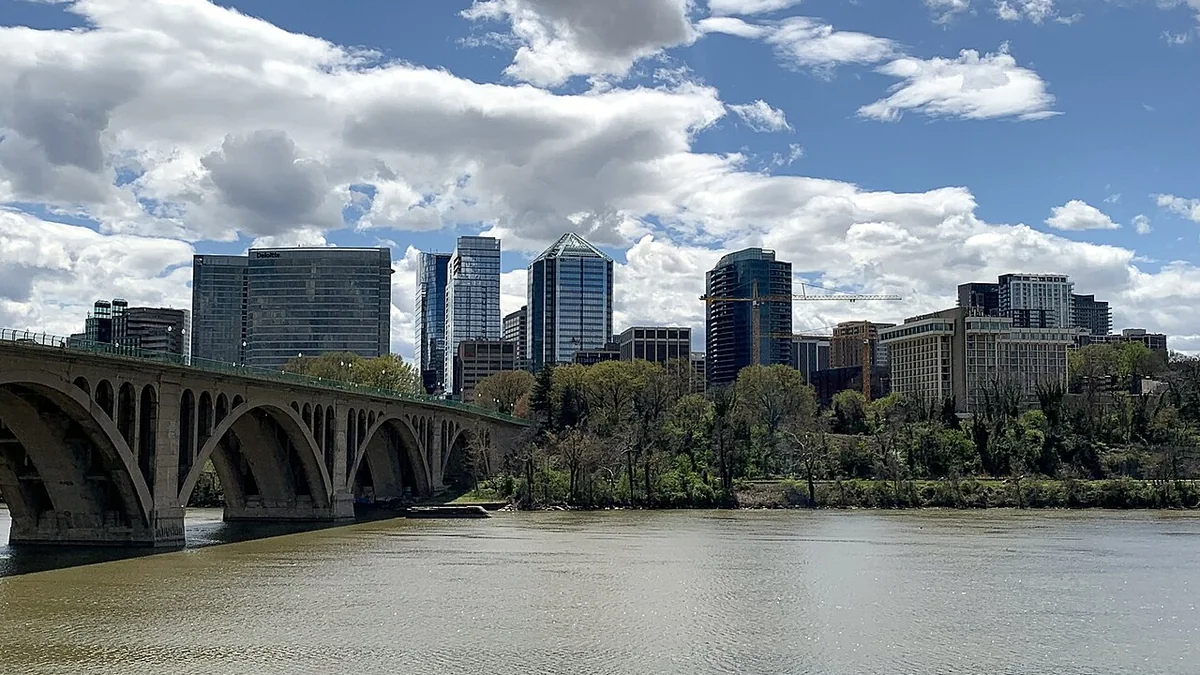
Photograph of Philadelphia, Pennsylvania
Philadelphia, Pennsylvania · 颐园居 · Original photo · CC BY-SA 4.0 · Cropped and resized.
PRIMARY STATE
Pennsylvania
REFERENCE JURISDICTIONS
Philadelphia, Montgomery, Bucks, Delaware and Chester
UPDATED
CENSUS · ACS 2025

Housing and income by statistical area

These figures cover the full metropolitan statistical area, including the counties shown below.

2025 ACS one-year estimates · 2025 dollars · 90% margins of error (±)
Indicator and Census table Philadelphia-Camden-Wilmington, PA-NJ-DE-MDCBSA 37980
Median owner-occupied home value B25077 $395,900 ± $3,690
Median monthly gross rent B25064 $1,638 ± $18
Median annual household income B19013 $95,683 ± $1,211
Median monthly owner cost with a mortgage B25088 $2,308 ± $22
Median monthly owner cost without a mortgage B25088 $891 ± $18
Homeownership rate B25003 66.8% ± 0.55 pp
Median share of income spent on gross rent B25071 30.6% ± 0.70 pp
Renters spending 30% or more of income on gross rent B25070 51.2% ± 1.79 pp
Households B25003 2,523,002 ± 9,734
Mean commute to work (minutes) B08013 · B08303 29.7 ± 0.56

Rent burden measures the share spending at least 30% of income on gross rent, among cash-rent households with a calculable share. “pp” denotes percentage points. Calculation method

Population and counties by area

Philadelphia-Camden-Wilmington, PA-NJ-DE-MD 6,329,118 residents in July 2025

+1.3% since the April 1, 2020 estimates base · Census profile

Census · Vintage 2025 population · Census · 2025 ACS geographic boundaries · How to compare ACS estimates

QUICK READ

What should you compare in Philadelphia?

For rowhouses, inspect shared walls, roofs, drainage, masonry and service lines; for condos and suburbs, add association, commuting and municipal-service analysis.

Build a useful comparison

Start with three or four areas compatible with daily life. For each, record the same evidence: housing type and age, price and concessions, actual taxes, quoted insurance, dues, utilities, likely maintenance, mobility, hazards and restrictions. Keep metropolitan, municipal and parcel-specific evidence separate.

Three priority checks

  1. 01

    Verify permits, tax balance and property records.

    Obtain the current assessor record and full tax bill, including every district or special charge. Ask the tax authority how a transfer, new construction or exemption change may affect the next bill.

  2. 02

    Inspect roofs, masonry and underground service lines.

    Walk the site and review seller records, permits and past repairs. Ask an independent inspector to distinguish maintenance from water, structure or envelope defects, then obtain specialist estimates for material findings.

  3. 03

    Compare city and suburban transfer costs.

    Obtain the current assessor record and full tax bill, including every district or special charge. Ask the tax authority how a transfer, new construction or exemption change may affect the next bill.

Visit as a researcher, not only as a buyer

Visit on a weekday and weekend, in daylight and after dark. Test the real commute, noise, parking, slopes, drainage, nearby construction, emergency access and everyday services. Separate personal observations, official evidence and marketing claims.

Frequently asked questions

01Is Philadelphia one real estate market?

No. The area contains municipalities, neighborhoods, housing types and jurisdictions with different costs, inventory and hazards. Compare the micro-market and parcel, not only the metro average.

02Which number should I verify first?

Start with the complete, verifiable cost of a specific property: price, current and future taxes, quoted insurance, dues, utilities, maintenance, commute and closing cash.

03Where do I verify a property in Philadelphia?

First confirm the municipality and county, then use the official portals for that address to check assessment, records, permits, zoning, hazards and professional licenses.

Where to check a property in Philadelphia

Philadelphia’s Atlas combines access to property, zoning, permit and inspection information by address. The separate Property App provides ownership, sales, valuation and physical-characteristic records.

Philadelphia — Atlas

Inspect address-level zoning, permit history and document links.

Philadelphia — Property App

Reconcile ownership, sale history and physical characteristics.

Use the property account number or registry map reference to reconcile results. A zoning layer, an assessment value and a permit status are different findings; preserve the underlying record for each question rather than treating one map view as complete due diligence.

FROM MARKET AREA TO JURISDICTION

The boundaries of this guide and your records

This is an editorial research guide, not a complete official definition of a metropolitan statistical area. Named places direct research and do not enumerate every component. Before comparing a figure, confirm whether it describes the municipality, county, planning region, metropolitan area or address.

State guides relevant to this research

For locations across a state line in the region, recheck taxes, title, licensing, insurance and rental rules against the property’s actual jurisdiction.

Compare state indicators · Accessibility and housing rights

HOUSING FINANCE AGENCIES

A housing-finance starting point for this area

State housing finance agencies are a starting point for researching affordable housing and homebuyer financing. Use the agency for the property’s state, then look up the specific program and its current application instructions.

A directory entry does not establish eligibility, funding availability or approval. Before relying on assistance, obtain the program terms: income and price limits, participating lenders, education, occupancy, repayment and any sale or refinancing trigger. A deferred loan is not the same as a grant. NCSHA · How to review an assistance offer